Richard Kirtley, Jun 19, 2026
A week ago, Purple Shoots helped a small business owner escape a loan that was costing her £12 per day in interest.
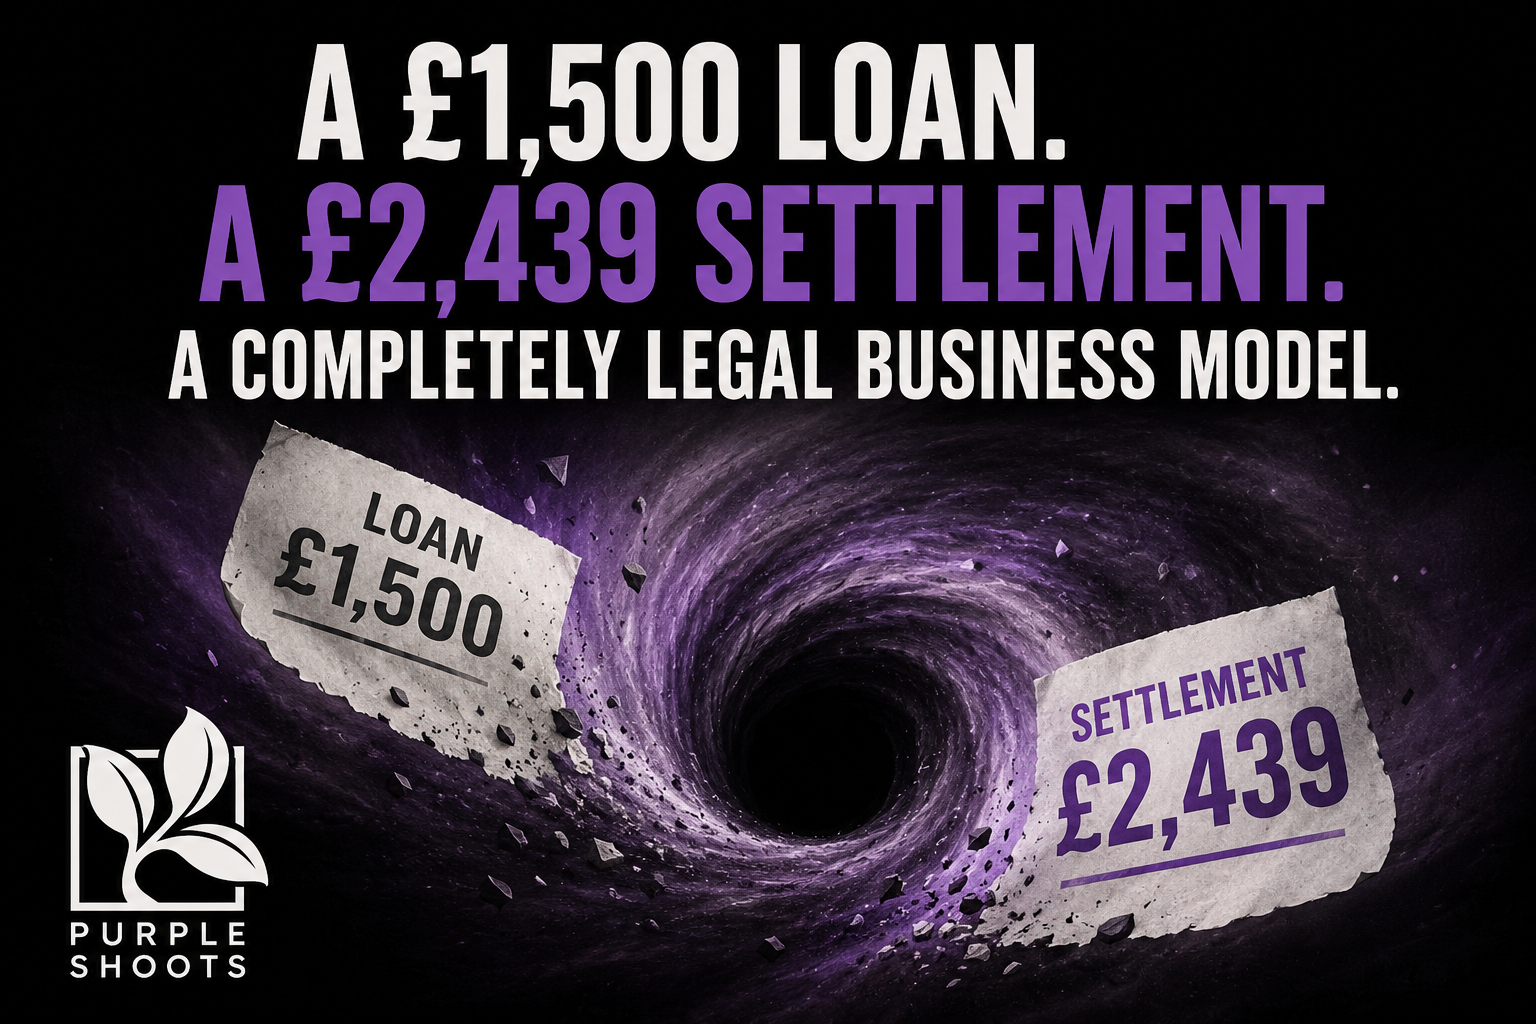
The original borrowing was £1,500. By the time we refinanced the debt, the settlement figure had reached £2,439 within 4 months! Had the loan remained in place, hundreds more pounds would have been extracted from her business over the coming months. This was not a loan taken out to fund a luxury purchase or an extravagant lifestyle. It was not reckless borrowing. It was not someone living beyond their means. It was a business owner trying to keep her enterprise afloat, caught in the gap between needing finance and being unable to access affordable alternatives. When mainstream finance closes its doors, people do not suddenly stop needing money. The need remains exactly the same. What changes is the cost.
What makes this story particularly troubling is that there was nothing illegal about it. This was not a loan shark operating from the shadows. This was not criminal lending. This was a fully regulated High-Cost Short-Term Loan provider operating under the oversight of the Financial Conduct Authority. Every box had been ticked. Every regulatory requirement had presumably been met. The lender was acting entirely within the rules. Yet that reality raises an uncomfortable question. If someone can borrow £1,500 and find themselves facing a £2,439 settlement figure, perhaps we should spend less time asking whether the lender complied with the regulations and more time asking whether the regulations themselves are achieving what they were intended to achieve.
The story becomes even more concerning when viewed in the wider context of what we are seeing across the market. In recent months, Purple Shoots has refinanced loans carrying annual interest rates of around 60%. Not payday lending. Not doorstep lending. Responsible personal lending. Sixty percent annual interest. A few years ago, most people would have considered that eye-wateringly expensive. Today, compared with some of the products available in the market, it almost feels moderate. That should concern all of us. When a 60% annual interest rate starts looking like one of the better options available, something fundamental has gone wrong in the way we think about access to finance.
Perhaps the most frustrating aspect of this entire debate is that the conversation almost always focuses on borrowers. We ask why people took the loan. We ask whether they understood the costs. We ask whether they should have looked elsewhere. What we rarely ask is where the money comes from in the first place.
High-Cost Short-Term Lenders do not generally fund themselves through goodwill. They are often backed by private equity firms, hedge funds, institutional investors, family offices and other sources of capital seeking strong financial returns. Many lenders also borrow money themselves through wholesale lending facilities, bank credit lines and institutional funding arrangements. In simple terms, capital may be sourced at relatively modest rates and then lent out to consumers at dramatically higher rates. The difference between those two figures is where much of the profit is generated. Some larger firms go further still, packaging up thousands of loans and selling the future repayment streams to investors, allowing financial markets to participate in the returns generated by high-cost lending.
This is the part of the story that rarely receives much public attention. Behind every high-cost loan sits an investor who has concluded that the returns are attractive enough to justify the risk….regardless of the damage it will inevitably cause. From a purely financial perspective, the logic is easy to understand. Demand is high. Customers often have limited alternatives. Margins are substantial. Loans turn over quickly. Even if a significant proportion of borrowers default, the overall economics can still be highly profitable. Viewed through the lens of an investment committee or fund manager, the business case can be compelling.
Yet this is precisely where the moral questions begin.
The debate is often framed as a choice between access to finance and no finance at all. We are told that these products exist because mainstream lenders have declined to serve these customers. There is certainly some truth in that argument. Risk is real. Not every loan will be repaid. Not every business will succeed. Lending to people with thin credit files, impaired credit histories or unstable incomes is more difficult than lending to affluent homeowners with substantial assets. But recognising risk is not the same thing as accepting any price attached to that risk.
At some point we have to ask whether our financial system has become extraordinarily good at monetising exclusion. The people with the fewest options often face the highest costs. Those with the least financial resilience frequently pay the most for access to capital. Those already under pressure are asked to shoulder the greatest burden. We have somehow constructed a system in which vulnerability often attracts a premium.
Imagine applying this logic elsewhere. Imagine charging more for food because someone had recently lost their job. Imagine increasing utility bills because a family had experienced illness. Imagine adding a surcharge to housing costs because someone had become a carer. Most of us would instinctively recognise the unfairness, and in fact would rage against such an injustice. Yet when the product being sold is money itself, I would argue that we have become remarkably comfortable with the idea.
This is not an argument that all high-cost lenders are acting unlawfully. Nor is it an argument that all investors in the sector are malicious. Many operate entirely within the law. Many genuinely believe they are providing a service that would otherwise not exist. But legality alone is a remarkably low bar for a society to set itself. The more important question is whether the outcomes produced by the system align with the values we claim to hold.
At Purple Shoots, we see every day what happens when people are offered something different. We meet individuals who have been rejected elsewhere, dismissed by algorithms, overlooked because their circumstances do not fit neatly into a credit model. Yet many of these same people go on to build successful businesses, increase household income, employ others and contribute positively to their communities. The issue is rarely a lack of potential. More often, it is a lack of affordable opportunity.
The real scandal is not that a lender charged £12 per day on a £1,500 loan. The real scandal is that for far too many people, this was one of the best options available. The real scandal is that investors can generate attractive returns from financial distress while community finance organisations struggle to attract the capital needed to offer fairer alternatives. The real scandal is that we have become so accustomed to these arrangements that they no longer provoke the public outrage they deserve.
Because when a small business owner borrows £1,500 and ends up facing a £2,439 settlement figure for a 6 month period loan, we should not simply ask whether the paperwork was compliant.
We should ask what kind of financial system thought that outcome was acceptable in the first place.